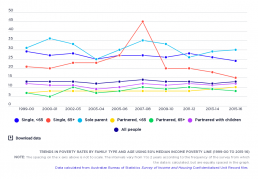
Trends in poverty rates by family type and age
[infogram id="_/U99pdeoM464V71vRaQNp" prefix="LT8" format="interactive" title="Fig.29_Trends in poverty rates by family type and age (1999-2015)"] This graph compares trends in poverty according to family type and age, between 1999-00 – 2015-16. It shows that, over this period, poverty rates were consistently higher for single people and sole parents than for partnered families. It also shows that poverty rates for people aged 65 and more, and for sole parents, were more variable than for other family types. The main shifts over the period are a decline in poverty among single people aged 65 and over; and a rise in poverty among partnered people, no matter their age. Poverty rates for single people fluctuated considerably more than for partnered people, especially for single people aged 65 and over, in part reflective of the closeness of single pension rates to the 50% median income poverty line.
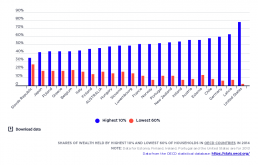
Household wealth distribution in OECD nations
[infogram id="_/qVhg7lrbYnQCgXJIgcw1" prefix="rLy" format="interactive" title="Fig.4_Wealth distribution in OECD nations in 2014"] In 2014, wealth was less unequally distributed in Australia than on average throughout the OECD, with 46% of household wealth in Australia held by the top 10% of households ranked by wealth. In contrast, income inequality is greater in Australia than in most OECD nations.
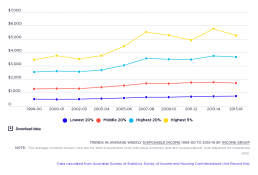
Trends in average weekly disposable income since 1999-00
[infogram id="_/GBas3Lc2Ku0noMRYn4jm" prefix="kcc" format="interactive" title="Fig.5_Trends in average weekly disposable income 2000 to 2016 (in 2016 dollars)"] This shows how average household incomes grew in ‘real terms’ (after inflation) for the lowest, middle and highest 20% income groups in Australia, as well as the highest 5%. It shows that income growth was very uneven during the boom from 1999-00 to 2007-08. The average income of the lowest 20% grew by 5.6% per year in real terms, compared with 5.9% for the middle 20%, 7.2% for the highest 20%, and 10.3% for the highest 5%. After the Global Financial Crisis, from 2007-08 to 2015-16, household incomes grew much more slowly and less unequally. The average household incomes of the lowest 20% grew by 2.5% per year (aided by a large pension increase in 2009), compared with 0.3% for the middle 20%, 0.8% for the highest 20%, and a decline of 0.6% for the highest 5% (likely due to falls in returns from investments.
Average income tax paid by households
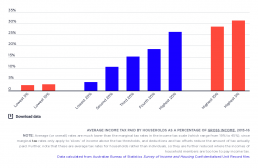
[infogram id="_/Ea6RLDekvwAqZpqCE5ZM" prefix="lWC" format="interactive" title="Fig.6_Average income tax paid by households as a % of gross income, 2015-16"] This shows the average (not marginal) tax rates paid by households (not individuals) in different income groups. Personal income taxes are progressive, so average tax rates increase with income. Households in the lowest 20% pay only 4% of their overall income in income taxes on average (including the Medicare Levy) compared with 15% for the middle 20% and 26% for the highest 20%. However, the progressive impact of income taxes is largely offset by the regressive impact of other taxes such as the Goods and Services Tax and Stamp Duties. Find out more.
Trends in wealth inequality by asset type
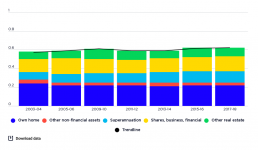
[infogram id="_/pLLmrjoss723BOzvS5ux" prefix="XO8" format="interactive" title="2017-18: Fig.20_Trends in wealth inequality (gini coefficient) by asset type from 2003-04 to 2017-18"] This graph shows the contribution of each asset class to overall wealth inequality, and how this changed over time. The sum of these contributions is the Gini coefficient for each year, which rose from 0.57 in 2003-04 to 0.62 in 2017-18. It also shows the contribution of different components of household wealth (asset classes) to overall wealth inequality. The three asset classes making the greatest contributions to wealth inequality at the end of the period in 2015-16 (when the Gini coefficient was 0.62) were owner-occupied housing (contributing 0.22, reflecting its high overall weight among household assets), shares and business income (contributing 0.15, reflecting its high concentration in high-wealth households), and superannuation (contributing 0.12, reflecting its high overall weight among household…
Comparison of household disposable incomes
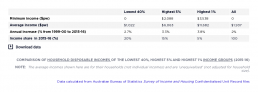
[infogram id="_/TcScbui4fV9kD1qlO8Yg" prefix="y1D" format="interactive" title="Table 1_Comparison of incomes of the bottom 40%, top 1% and top 5% (2015-16)"] This table compares the minimum and average household incomes of the lowest 40% income group, the highest 5% and the highest 1%. In 2015-16, the average household income of the highest 1% was $11,682 per week, over ten times the average disposable income of the lowest 40% , which was $1,022 per week. Their incomes were almost twice that of the highest 5% and almost six times the overall average household disposable income ($2,033). The incomes of the highest 1% of households also increased more rapidly. Between 1999-00 and 2015-16, their average incomes rose 15% faster than the incomes of households in the highest 5%; and 42% faster than the lowest 40%.
Components of Australia’s wealth
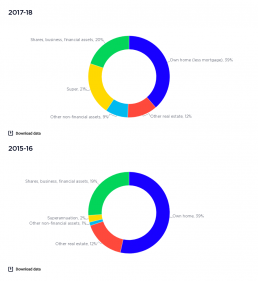
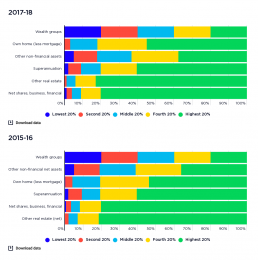
Ths graph shows the parts of Australia's wealth. [infogram id="_/OW0OGoFSiCC4l3IVwCVu" prefix="xD9" format="interactive" title="2017-18: Fig.14_Components of Australia’s wealth"] 2017-18: 39% of household wealth is held in owner-occupied housing, 12% in investment property, 21% in superannuation another 20% in shares and other financial assets (such as bonds and bank accounts), and 9% in other non-financial assets such as cars. 2015-16: A large component of Australia’s household wealth (39%) is held in the family home, followed by 20% in superannuation , and 19% in financial assets such as shares and business assets. Around 12% is held in other real estate – investment properties - and 10% in other non‑financial assets such as vehicles and home contents.
Shares of wealth across wealth groups by asset type
This graph shows how different types of wealth holdings are distributed across wealth groups. It shows that ownership of shares, investment real estate and superannuation is highly concentrated. [infogram id="_/E0NBFngbco6CKd2ZGEwy" prefix="MaQ" format="interactive" title="2017-18: Fig.16_Shares of wealth across income groups by asset type (2016)"] 2017-18: The wealthiest 20% group holds 81% of shares and other financial investments; and 83% of investment property. Superannuation is also shared unequally, with 61% by value held by the highest 20%, and 20% held by the next highest wealth group. Owner-occupied housing is more equally distributed, with 55% by value held by the highest 20%, and 27% by the second-highest wealth group. 2015-16: The highest 20% of the wealth distribution owns over 80% of all wealth in investment properties and shares and over 60% of all superannuation assets. Household wealth in the residential home is more evenly distributed, though the highest 20% still…
Trends in real average household disposable income since 1999-00
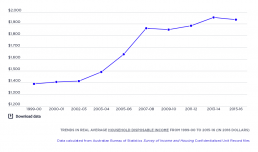
[infogram id="_/HBJ5SXNoKbAAq7gJ98cs" prefix="3NF" format="interactive" title="Fig.1_Trends in real average household disposable income from 1999-00 to 2015-16 (in 2016 dollars)"] This shows how average household disposable incomes have grown in ‘real terms’ (after inflation) in Australia between 1999-00 and 2015-16. During the boom period from 2000 to 2008, average household disposable income grew by a remarkable 4.3% per year in real terms. This reflected rapid overall economic growth underpinned by mining and housing booms. However, in 2008, the Global Financial Crisis cut economic growth by half. This reduced average disposable income slightly the following year. Average income then slowly increased, and dropped slightly again in 2015-16.
Comparison of income support payment rates and poverty lines
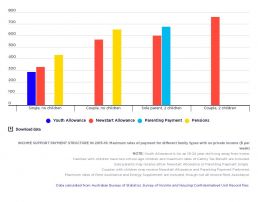
[infogram id="_/I3NcQQUxo5RWbDHkGtCa" prefix="fnx" format="interactive" title="Fig.17_Social security payment structure in 2015-16: maximum rates of payment for different family types with no private income ($ per week)."] Government payments in Australia include income support payments for adults in low income households (divided into the higher pension payments such as Age Pension and lower allowance payments such as Newstart Allowance), Family Tax Benefits for children in low and middle-income families, and supplementary payments such as Rent Assistance for private tenants in low-income households. This graph illustrates the rate structure that applied in 2015-16.