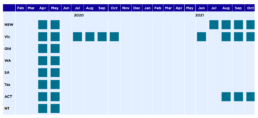
Overview of pandemic economic shutdowns by jurisdictions
[infogram id="_/tc62J1fu89uVqv1KcAHk" prefix="qNU" format="interactive" title="Figure 3.1"] This table shows the timeline of pandemic economic impacts in Australia's 8 state/territories. Crucial here have been the lockdowns that have impeded economic activity, with major implications for employment and incomes, as well as specifically for property transactions. The most significant point of this table is that Victoria alone experienced a long and economically damaging lockdown in the second half of 2020 – an experience which appears to have been reflected in some of the rental market patterns highlighted in subsequent graphs.
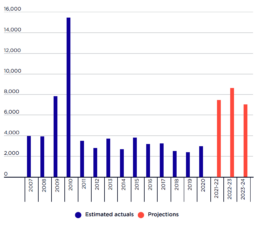
Actual and projected new social housing commencements, Australia, 2007 - 2023-24
[infogram id="_/y8W1Lx3LydCJqqVj7fyu" prefix="yQ4" format="interactive" title="Figure 6.3"] The projected annual rate of social housing construction 2021-22 – 2023-24 represents almost a threefold increase over the pre-pandemic benchmark rate (7,750 versus 2,610).
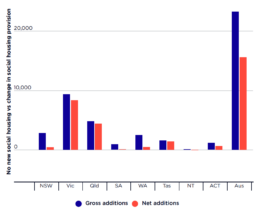
Projected social housing commencements 2021-22 – 2023-24, and projected net change in social housing provision
[infogram id="_/GDU8H3Nem83a4rOG7nPU" prefix="Nje" format="interactive" title="Figure 6.5"] Despite the significant increase in overall social housing construction anticipated over the next three years, the resulting net change in provision will be inadequate to prevent a further reduction in the sector’s share of all housing, Australia-wide. According to our projections this will decline from 4.22% to 4.14% of estimated total dwelling stock over the period.

Quarterly asking median rent per week, houses
[infogram id="_/OG0cS8DrTfUaqW0RTY8Q" prefix="JE6" format="interactive" title="Figure 4.11 quarterly median asking rent per week houses"] This graph shows that in every state capital except Hoabrt, the median asking rent for houses increased during the September quarter 2020 to at least the same level as before the pandemic; and in several cities increased to a greater level.
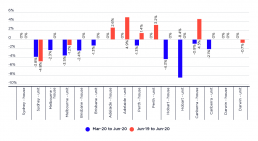
Change in median asking rents, quarter on quarter and year on year to June 2020
[infogram id="_/be00vY7THWxA0hDvPNQm" prefix="Lme" format="interactive" title="Figure 4.10 Change in median asking rents"] This graph compares hte decline in median advertised rents from both the first quarter of 2020 and the June quarter of 2019 for both houses and units in each of the state capitals, showing the immediate impact of the pandemic on unit rents in Sydney, Melbourne and Hobart. Only in Sydney and Melbourne did asking rents fall to lower than the median price for the same time the previous year. In contrast, the effect on median asking rents for houses was much smaller, barring Hobart. In Adelaide, Perth and Canberra, median asking rents remained higher than they had been during the June quarter of 2019.
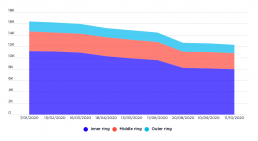
Airbnb listings for entire houses, Melbourne, January to October 2020
[infogram id="_/4XBohK9wv6rsW9PxaYK9" prefix="07j" format="interactive" title="Figure 4.9 Airbnb listings for entire houses Melbourne"] This graph shows the data for listings from InsideAirbnb for Melbourne during the period January to October 2020. It shows that listings for entire homes contracted by 22% since COVID-19 restrictions were introduced, equating to 3,661 dwellings that were presumably available previously for long term lease or purchase. The decline is most pronounced in the inner rings of Melbourne. It suggests that, while many of these properties might have been sold, re-occupied by owners, or left unoccupied, there was likely a substantial increase in the supply of longer term private rental properties in inner-Melbourne.
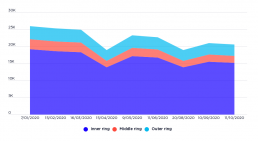
Airbnb listings for entire houses, Sydney, January to October 2020
[infogram id="_/hXNj18OkFGRLjP2tMKhL" prefix="qgY" format="interactive" title="Figure 4.8 Airbnb listings for entire houses Sydney"] This graph shows the data for listings from InsideAirbnb for Sydney during the period January to October 2020. It shows that listings for entire homes contracted by 17% since COVID-19 restrictions were introduced, equating to 4,317 dwellings that were presumably available previously for long term lease or purchase. The decline is most pronounced in the inner rings of Sydney. It suggests that, while many of these properties might have been sold, re-occupied by owners, or left unoccupied, there was likely a substantial increase in teh supply of longer term private rental properties in inner-Sydney.
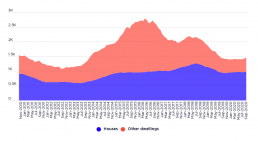
New private dwelling approvals, Greater Brisbane
[infogram id="_/ysDjqpnVzeFaUJvT89a6" prefix="nMA" format="interactive" title="Figure 4.7 New private dwelling approvals, Greater Brisbane"] This graph shows how apartments and units became the main source of new dwellings in the Greater Brisbane area over 2013-14 to 2015-16.
New private dwelling approvals, Greater Melbourne
[infogram id="_/vsCL2pcuFSeuAiAXkgPd" prefix="sJ2" format="interactive" title="Figure 4.6 New private dwelling approvals, Greater Melbourne"] This graph shows how apartments and units became the dominant source of new dwellings in Greater Melbourne over 2013-14 to 2015-16.
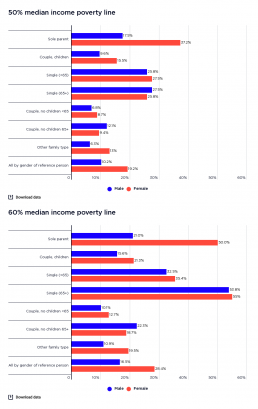
Rate of poverty by gender of household reference person (% of all people)
This graph shows the rate of poverty according to the gender of the household reference person by household type.[infogram id="_/0v0XLUr2FLIpHKZdoFDv" prefix="Jvp" format="interactive" title="Figure A1: Rate of poverty by gender of household reference person (% of men and women), 50% median income poverty line"] It shows that the rate of poverty in sole parent families where the main earner is female is 37% using the 50% median income poverty line, and 50% using the 60% median income poverty line. This is over twice that of sole parent families where the main earner is male (at 18% using the 50% median income poverty line and 21% using the 60% median income poverty line). It also shows that couple-with-children households where the main earner is female have a rate of poverty far higher than those in which the main earner is male (16% female and 10% male according to the 50% median income poverty line; and 21% female and 16% male according to the 60% median income poverty line). The…